The Gulf and North Africa are about to get a lot more places to stay. New figures from hospitality consultancy HVS show roughly US$90 billion of hotels and resorts in the pipeline across the GCC and North Africa — around 200,000 new rooms that would grow the region's existing supply by 27%. Just over 88,000 of those rooms are already under construction, with another 25,000 at final planning stage, and more than half of the new hotels are due to open by 2030.
Saudi Arabia is the engine of the expansion, accounting for about 110,000 rooms — half the regional total. The building covers Riyadh, the pilgrimage cities of Makkah and Madinah, and the giga-projects: Diriyah, NEOM, the Red Sea and AMAALA. What's notable is the range: alongside big pilgrimage hotels, developers are pushing luxury resorts, branded residences and upper midscale brands like Hampton by Hilton, Holiday Inn Express, Fairfield by Marriott and ibis, aimed at making the kingdom affordable to more than just premium travellers.
Egypt ranks second with 42,000 rooms planned across Cairo, the Mediterranean North Coast and Red Sea resorts, plus newer mixed-use destinations. The UAE comes third, and as a mature market it's adding selectively — Dubai, Abu Dhabi and Ras Al Khaimah, where the Wynn Al Marjan Island resort is one of the headline projects.
Don't expect a sudden flood of openings. Rooms will arrive in phases, with about 44% already being built and the rest trickling through to 2030 and beyond. Saudi mega-destinations in particular will deliver well into the next decade, while UAE openings cluster around 2028-2030 and Egypt's cycle is spread over several years.
The money behind all this has changed too. HVS says capital is being deployed more carefully than in past booms, favouring mixed-use schemes, branded residences and phased builds that spread risk. In Saudi Arabia, government-backed investment vehicles and public-private partnerships are underpinning the biggest destination projects, replacing the old developer-equity-plus-bank-loan model.
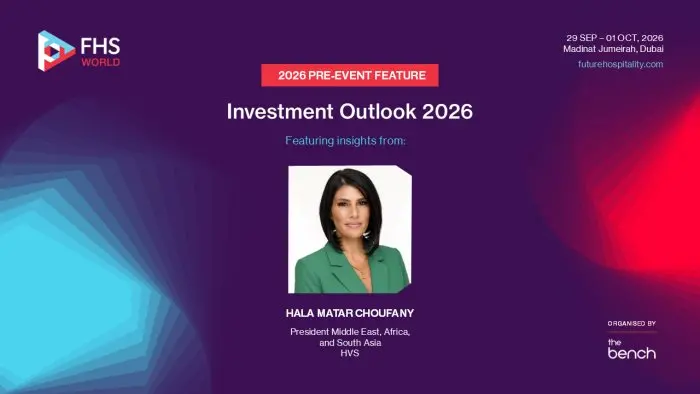
For travellers, the practical takeaway is choice. The luxury and upper-upscale segment still dominates the pipeline, so the region keeps adding serious high-end inventory — but the growth of upper midscale brands, especially in Saudi Arabia, means newly opened destinations like the Red Sea coast are becoming reachable on a normal holiday budget rather than a billionaire's. As HVS's Hala Matar Choufany points out, the next test is whether new rooms come with the airlift, transport links and service quality to fill them — which, if it happens, means easier flights and better competition on rates for visitors.
If you like being early to a destination, the window is now: places like NEOM's coastline, AMAALA and Egypt's North Coast will feel genuinely new for the next few years, with hotel counts — and competition for your booking — rising sharply towards 2030. The data was released ahead of Future Hospitality Summit World, running at Madinat Jumeirah in Dubai from 29 September to 1 October 2026.