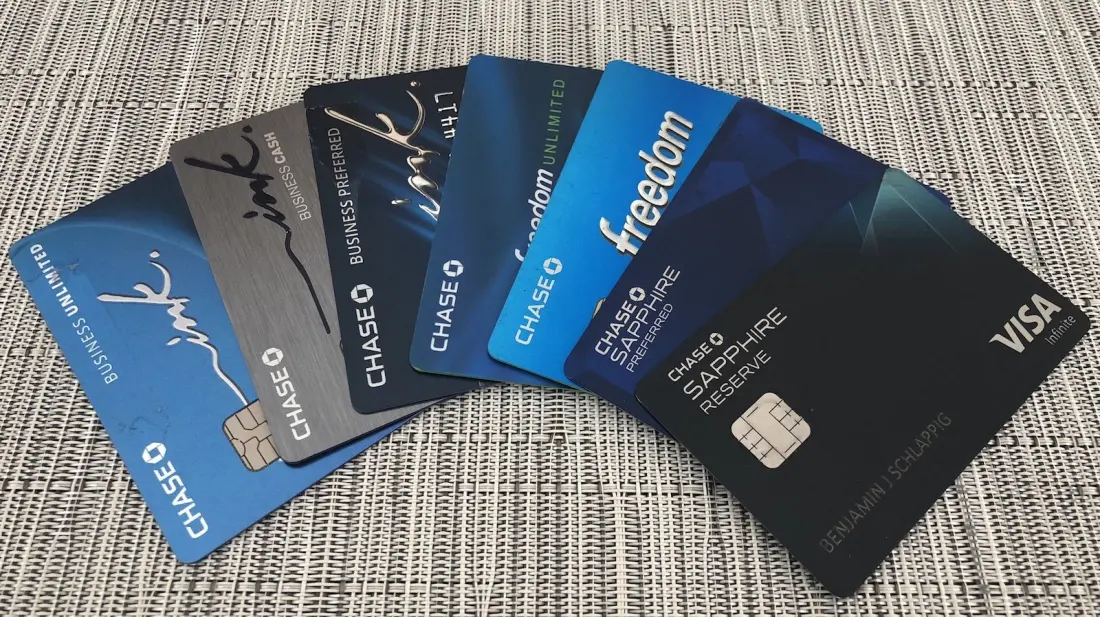
Chase issues some of the most rewarding travel credit cards around — the Sapphire Reserve and Preferred, the United and Southwest co-brands, the World of Hyatt card — but it also has one of the strictest approval policies in the business. It's called the 5/24 rule, and if you've opened five or more new credit card accounts in the past 24 months, Chase will usually decline your application, no matter how good your credit score is.
The rule applies across Chase's whole portfolio, personal and business alike, including co-branded cards like the Aeroplan, Iberia, Aer Lingus, IHG and Marriott Bonvoy options. The logic, though Chase has never confirmed it, is that customers who open lots of cards are more likely to be bonus-chasers who churn and leave, while those under the limit tend to stick around and stay profitable.
Not everything counts toward your total. Any personal card opened in the last two years counts, regardless of the bank — including store cards and cards where you're merely an authorized user. Most business cards, however, don't show on your personal credit report and therefore don't count, with a few exceptions such as Discover, TD Bank, and some Capital One business cards like the Venture X Business. Loans, rejected applications and closed cards don't add to your count either — and note that closing a card doesn't remove it from your 24-month history. One quirk worth knowing: a Chase business card is subject to the rule but doesn't itself push you over it, so you can stack multiple business approvals while staying at, say, 4/24.
Enforcement isn't quite as iron-clad as it once was — there's been a growing stream of reports of people approved despite being over the limit — but the safe assumption is that the rule applies to you. There are a couple of loopholes: targeted "Just for You" offers in your Chase account sometimes bypass it, and calling the reconsideration line to argue that authorized user accounts shouldn't count occasionally works. The most reliable route over the limit is a product change on a card you've held for at least 12 months, though that forfeits the welcome bonus.
To check where you stand, a free Credit Karma account is currently the easiest method: click your credit score, open the "Credit age" section, and count the cards opened in the past two years. Just remember it only shows currently open accounts. And when you do fall back under the limit, wait until the first day of the 25th month after that fifth application — the counter doesn't always reset instantly.
For anyone plotting points-funded flights and hotel stays, this is the single most important thing to understand before applying for a Chase card. Get the sequencing right — business cards first, personal cards strategically, a simple spreadsheet to track it all — and the sign-up bonuses on these cards can cover serious travel. Get it wrong and you'll burn a hard inquiry on an instant denial.
First reported by One Mile at a Time