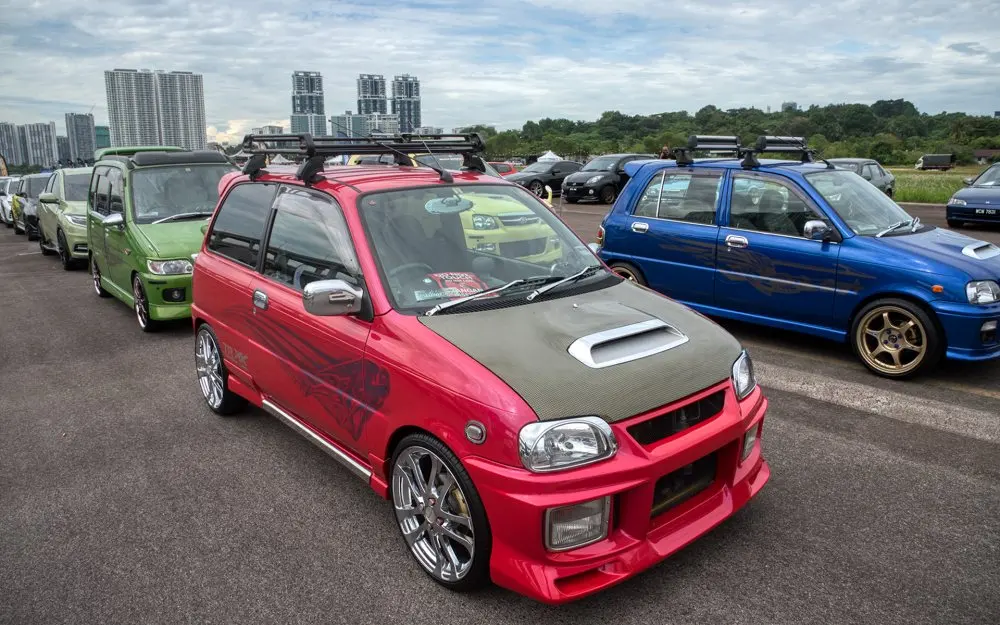
A recent enforcement sweep in Kuala Lumpur has put modified cars back under the spotlight — and it's not just about fines. During Ops Ekstrem earlier this month, Malaysia's Road Transport Department (JPJ) seized 37 vehicles with extreme modifications, while the same operation logged 57 offences involving uninsured vehicles. The message for drivers is twofold: keep modifications legal, and make sure your insurer knows about them.
Here's the part many owners miss. Sport rims, lowered suspension, body kits, turbochargers and performance upgrades don't just change how a car looks or handles — they can change your insurance premium, your coverage, and whether a claim gets paid at all. Modified car insurance simply means cover for a vehicle altered from its factory specifications, and any change affecting the engine, suspension, performance or high-value wheels can shift the car's value, repair cost and risk profile.
The General Insurance Association of Malaysia (PIAM) is clear on the rules of thumb. Modifications that increase accident risk may push premiums up — or lead an insurer to decline cover altogether. More seriously, if you didn't disclose a modification and that modification contributes to an accident, your insurer may have grounds to reject the claim. In other words, an undisclosed exhaust or engine tune could leave you personally footing a very large bill.
Not all mods are treated equally, though. Cosmetic tweaks are generally assessed differently from engine or performance work, and insurers will look at whether aftermarket parts — custom rims, body kits, performance components — cost more to replace than stock equivalents. Coverage for those parts depends on your specific policy terms, limits and exclusions, so it pays to read the fine print before assuming everything is included.
Ronald Lim, CEO of insurance comparison platform BJAK, puts it bluntly: a mod that looks like a simple upgrade to the owner can change the vehicle's value, repair cost and risk from an insurance perspective — and you want to understand that before an accident, not at claim time. His platform lets drivers compare car insurance and takaful options from up to 16 providers, with terms for modified cars varying by insurer and policy.
For travellers and expats driving in Malaysia — or anyone renting long-term or importing a car — this matters more than you might think. Road trips from Kuala Lumpur to the Cameron Highlands or up the east coast are popular, and accidents on those routes do happen. If you've fitted new wheels or a roof box system to your own car, a quick call to your insurer before renewal is cheap insurance in itself. Review your sum insured, compare premiums and benefits, disclose what's been changed, and confirm aftermarket components are actually covered. A few minutes of paperwork beats a rejected claim after a breakdown or a prang.