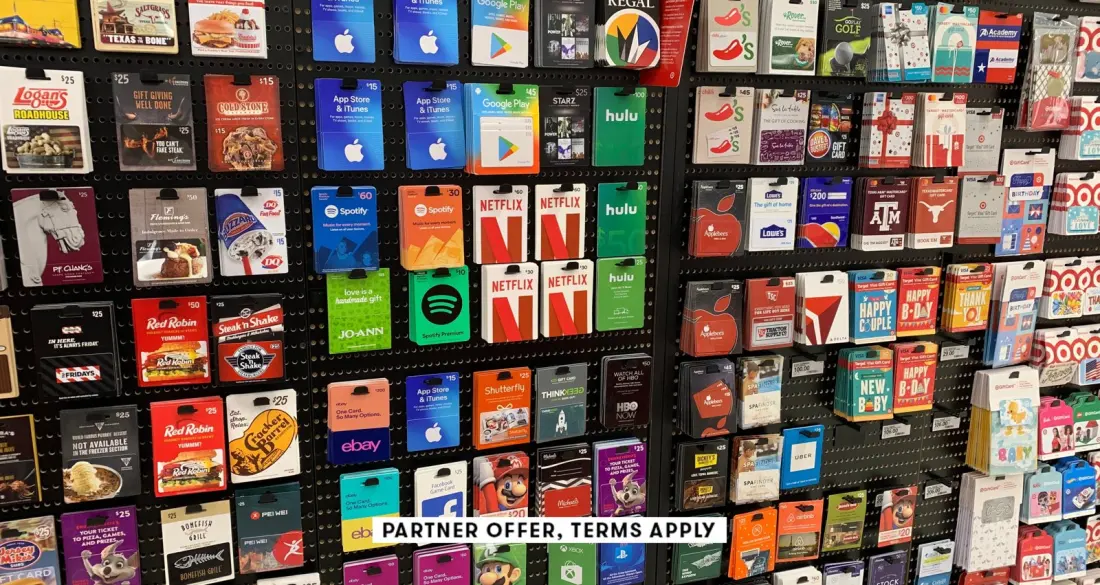
Gift cards are an underrated trick in the points-and-miles playbook. Buy an Airbnb card before a trip, or a supermarket gift card before a big grocery run, and the purchase can still count toward your card's bonus categories — turning everyday gift buying into free travel fuel. The Points Guy has rounded up five cards from five different issuers that make the most of it.
The standout is Chase's Ink Business Cash: no annual fee, 5% back at office supply stores like Staples and OfficeMax on the first $25,000 of spending each year, plus a $750 cash welcome offer after $6,000 of spend in three months. Office supply stores stock gift cards for dozens of brands, which is why this card is a favourite among small business owners. If you also hold a premium Chase card, those rewards can be transferred to one of 14 airline and hotel partners.
The American Express Gold earns 4 points per dollar at U.S. supermarkets (up to $25,000 per calendar year), so gift cards bought at the grocery till earn big — even though the card carries a $325 annual fee, offset partly by dining credits, Resy credits and monthly Uber Cash. A current welcome offer can reach 100,000 points after $8,000 of spend in six months.
Prefer cash back? Bank of America's Customized Cash Rewards pays a hefty 6% in the category of your choice for the first year (capped at $2,500 per quarter), then a still-solid 3% after that, with no annual fee and a $200 bonus. Costco shoppers have a niche problem — warehouse clubs rarely trigger bonus categories — so the Costco Anywhere Visa from Citi is often the only way to earn, paying 2% back at Costco and Costco.com, though you'll need a membership and rewards arrive only as a once-a-year certificate.
For simplicity, the Citi Double Cash earns 2% on absolutely everything (1% at purchase, 1% on payment), making it the fallback card when a gift card seller doesn't fit any bonus category. Its rewards come as ThankYou points, which can be transferred to 21 airline and hotel partners.
One caution the source flags: don't use a single card only for gift card purchases. Issuers can view that pattern as gaming the system, and in the worst case your account could be shut down. Mixed spending is the safe approach.
For travellers, the logic is simple — a few thousand dollars of gift card spending a year at 4-5% back is a meaningful boost toward a flight or hotel redemption, and it costs nothing extra if you were buying those cards anyway.