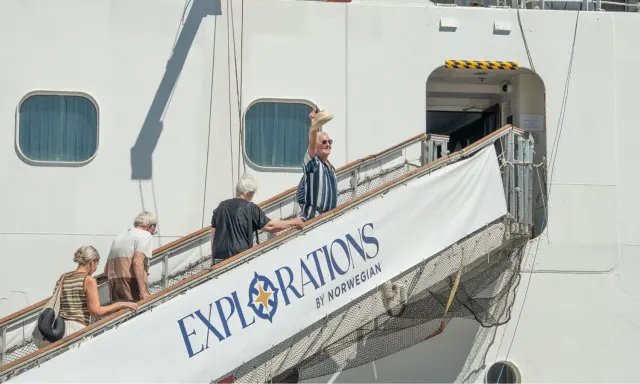
Buying a cruise usually involves weeks of happy research — comparing ships, cabins and shore excursions. Insurance, by contrast, tends to be a last-minute click. Cruise Passenger, the Australian cruise title, is trying to change that by teaming up with insurer 1Cover to collect readers' insurance questions and put them to specialists, with answers to be published in an upcoming reader guide.
The push targets some genuinely costly blind spots. The biggest: assuming a domestic cruise doesn't need cover. Onboard doctors on ships sailing between Australian ports generally operate privately, so Medicare and private health insurance often won't apply — even in home waters. Passengers can be billed upfront for consultations, medication and scans, and if things get serious, a medical evacuation may be required. Australia's Smartraveller service warns that a helicopter evacuation from a cruise ship can run to hundreds of thousands of dollars, and advises checking whether the ship's doctor is Medicare-accessible and whether your policy covers evacuation at sea.
Age is the other sticking point. Contrary to popular belief, plenty of insurers will cover travellers into their 80s, and some have no fixed upper age limit on selected policies. But premiums, excesses, trip-length caps and medical screening all shift with age — and the cheapest policy on the comparison site is often the one that quietly excludes the condition most likely to land you in the ship's hospital. Pre-existing conditions such as heart disease, diabetes or past cancer treatment need to be declared, and cover for them varies widely between insurers.
The fine print extends well beyond medical cover. Policies can contain clauses about alcohol, independently booked shore excursions, missed ports, mobility scooters and unattended luggage, and many require you to call the insurer before approving expensive treatment. Credit-card insurance is a particular trap: cover may need activating, a minimum portion of the trip may need to be charged to the card, a travelling partner might not automatically be included, and age or medical restrictions can still apply. The government's Moneysmart service recommends a careful read of the Product Disclosure Statement — easier said than done with a document full of definitions and exclusions.
Cruise Passenger is inviting readers to submit both questions and real-life claims stories — good and bad — via a form on its site, with the option to stay anonymous. Suggested topics include cruise-specific cover for coastal voyages, which insurers cover travellers over 80 or 90, whether policies pay out in full for helicopter evacuations, cover when a companion falls ill, and what happens if you miss the ship or the ship skips a port. Note the caveat: don't send confidential medical, policy or financial details.
For anyone booking a cruise this year — especially older travellers or those with existing health conditions — this is a chance to get clear answers before buying rather than at the moment of a claim. And for everyone else, the message is already clear: even a cruise that never leaves Australian waters is a private medical environment, and insurance is the one purchase you'll hope never to use but shouldn't book without.