Launching a business means spending money whether you like it or not — software, shipping, ads, travel, even the rent on your home office. The upside, as The Points Guy lays out in a recently updated guide, is that almost all of it can be put on a credit card that earns points, miles or cash back. The trick is matching the card to where your money actually goes.
The guide's core advice is simple: pay for business costs you'd incur anyway with cards that reward those categories, chase welcome bonuses by meeting their spending requirements with real expenses, and always pay balances in full — interest and processing fees can wipe out any rewards you earn. Watch for caps, too. Several popular cards only pay bonus rates on the first $150,000 (or $25,000) of combined spending each year, so heavy spenders need to plan around those ceilings.
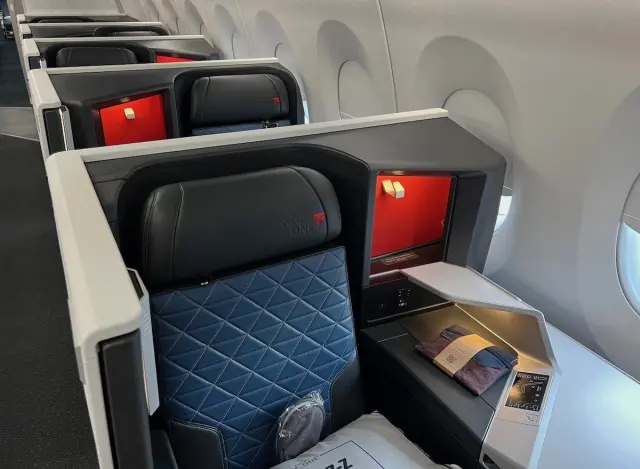
For travel-heavy businesses, premium cards do a lot of the work. The Amex Business Platinum earns 5 points per dollar on flights and prepaid hotels booked through Amex Travel, and piles on perks: an annual $200 airline fee credit, up to $120 toward Global Entry, access to more than 1,550 lounges in 140 countries, and up to $600 a year in lodging statement credits on prepaid Amex Travel bookings. Its $895 annual fee only makes sense if you'll use those benefits. The Capital One Venture X Business is a lighter alternative at $395, with 10 miles per dollar on hotels and rental cars booked through Capital One's portal and a flat 2 miles per dollar on everything else.
Different spending patterns call for different cards. If you buy a lot of office supplies and phone or internet service, the Chase Ink Business Cash pays 5% back on the first $25,000 in those categories, and its sibling, the Ink Business Preferred, adds 3 points per dollar on travel, shipping and advertising on social media and search engines — useful if you're running Facebook or Google campaigns. For ad spend specifically, the Amex Business Gold's flexible structure lets advertising on U.S. media providers count as one of your top two bonus categories.
There's a niche option for home-based founders: Bilt. Its cards let you earn up to 1.25 points per dollar on eligible rent or mortgage payments with no transaction fee — provided you also spend at least that much on everyday purchases each billing cycle. Points transfer to airline and hotel partners, and housing rewards only cover residential properties, not commercial offices.
Who should care? Anyone in the early months of a venture — freelancers, side-hustlers, small business owners — who wants their overhead to fund the next holiday. The strategy matters more than any single card: tally where your money goes, pick one or two cards covering those categories, and treat rewards as a bonus, not a reason to carry debt. Done right, filing your invoices becomes the first step of your next trip.
Full details on earning rates, caps and fees are in the original guide from The Points Guy.